Posts

Q3 Medical Office Building Sales Were $2.2 Billion

After a slow start to the year, medical office building (MOB) sales have picked up in the second and third quarters (Q2 and Q3), providing a strong possibility that the final 2019 volume will top $10 billion for the fifth straight year.

According to two data firms that separately compile their own MOB sales statistics – Arnold, Md.-based Revista and New York-based Real Capital Analytics (RCA) – transaction volume in Q3 topped $2 billion. Both firms’ data shows that year-to-date (YTD) MOB sales through Q3 topped $7.1 billion.

RCA’s data had Q3 MOB sales at $2.35 billion, for a YTD total of $7.28 billion. The firm’s data also indicates that the average capitalization (cap) rate, or the expected first-year yield, in Q3 was 6.7 percent – up from 6.3 percent in Q2 – and the average price per square foot (PSF) of $316, which was down from $326 a quarter earlier.

Revista, which uses different criteria for compiling its MOB sales data than RCA, indicates that Q3 sales totaled $2.2 billion, bringing the YTD total to $7.1 billion. Revista’s data shows that the overall average cap rate for MOB sales was about 6.6 percent in Q3, with the average cap rate for MOB portfolio sales coming in at 6.2 percent and single assets at 6.8 percent. Revista data puts the average PSF for all MOB sales at $323.

Interestingly, Revista data shows that there is still a premium to be paid for on-campus MOBs, which sold for an average of $339 PSF; on the other hand, off-campus facilities had an average PSF of $321.

Revista’s data also indicates the highest quality properties, those in the top 25 percent, sold for average cap rates of 5.8 percent and the absolute highest quality properties selling for cap rates averaging 4.4 percent.

While the YTD MOB sales volume stood at more than $7 billion at the end of Q3, there is a good chance that Q4 will see a strong uptick in volume. This news come by way of a variety of industry professionals as well as 2019’s biggest buyer by far, Toledo, Ohio-based Welltower Inc. (NYSE: WELL).

As HREI reported on Nov. 13, Welltower, which had made MOB investments topping $2 billion YTD through the end of Q3, last week announced that in recent weeks it had entered into five separate definitive agreements to acquire MOBs for a combined total of $1.67 billion.

Welltower’s pending acquisitions, for which it has entered definitive agreements, includes a $787 million purchase of 29 “Class A” MOBs from Milwaukee-based Hammes Partners. In addition, the REIT announced that it is “under contract” to make four other, separate MOB transactions totaling $885 million.

Those purchases, if they close as predicted by the end of year, would bring Welltower’s total 2019 MOB acquisitions to more than $3.5 billion.

Welltower’s deals alone, should they indeed close by the end of the year, would bring the MOB sector’s overall volume for the year, when added to the $7 billion-plus recorded in the first three quarters, to nearly $9 billion and provide a virtual lock that 2019’s volume will exceed $10 billion once again.


Source: HREI
Healthcare Real Estate Offers Superior Returns

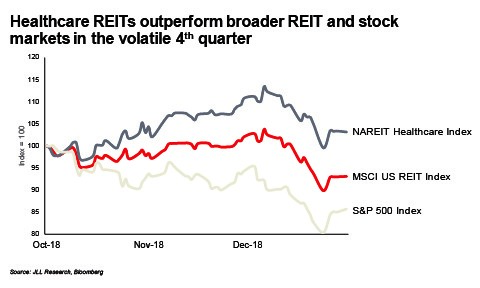
Healthcare REITs outperformed the broad REIT Index and S&P 500 in the fourth quarter 2018, a period of great volatility when equity markets fell 20% at one point.

The NAREIT Healthcare Index closed the year up 3% from the start of the quarter with the S&P 500 ending down 14% and the broad REIT index off 7%.  Healthcare’s positive share movement is linked closely to the movement in U.S. Treasury yields; with 10-year rates declining from 3.05% to 2.68% during the quarter, investor appetite for returns from healthcare REITs grows.

The performance of the healthcare sector’s real estate offerings is a clear reflection that the growing demand for healthcare and long-term care is largely independent of the economy.  Healthcare real estate features long-term leases with predictable income from service providers fulfilling critical medical needs that continue even in an otherwise unpredictable market.

REITs such as Welltower have taken advantage of their buying power during this period, announcing sizeable acquisitions including the $1.25 billion CNL medical office portfolio with 55 buildings totaling 3.3 million square feet as well as more than $500 million of strategic medical office investments.

Healthcare REITs are using more ingenuity to stay in the game for acquisitions through strategic joint ventures.  HCP formed a $605 million joint venture with Morgan Stanley in August 2018 for a 2 million square foot medical office portfolio which included the acquisition of 16 buildings totaling 856,000 s.f. leased to Greenville Health, acquired from Healthcare Trust of America.  Healthcare REITs vie for strategic health system relationships to develop critical scale and future investment and development opportunities with market-leading providers.

While private equity dominated healthcare competitively through much of 2018 as REIT share values lost ground with the rise in U.S. Treasury yields, the fourth quarter is a reminder of how quickly the table can re-set.  The disciplined strategies of certain healthcare REITs and the surplus of capital chasing healthcare properties today is testimony to the durability of this relatively stable property class.  With economic and market uncertainty, the reliable cash flows of healthcare properties supported by the steady forces of a growing and aging population, make this sector a strong defensive play in today’s market.


Source: Wolf Media USA

Healthcare REITs Signal An Increased Focus On Medical Office

It is earnings season, which means real estate companies are diligently releasing their earnings and analysts are intently scrutinizing said reports. Mizuho REITs analyst Richard Anderson covers healthcare REITs and he noticed a trend among the big 3 companies HCP, Welltower and Ventas in their recent releases: they all are emphasizing strategies involving medical office buildings.

To be sure, MOB is a staple among their holdings but as Anderson tells GlobeSt.com, “it just seemed interesting that each of the three highlighted a very specific strategy aimed at approaching the medical office business to some degree, versus past earnings reports.”

He says that:

  • HCP made mention of its joint venture with Morgan Stanley that’s aimed at investing in medical office as well as a new partnership with HCA to focus on the asset class.
  • Welltower is expected to close about $500 million of MOB transactions in the short term. “Also, they have always talked about using their senior housing portfolio as a quasi hanging carrot for medical office, as a medical office feeder.” The REIT has also brought on board a former Duke Realty executive Keith Knokoli, who has strong credentials in the MOB segment. “You don’t make an investment at that level of executive if you’re not serious about the business.”
  • Ventas is re-igniting its exclusivity arrangement with PMB Real Estate Services. It is a medical office developer that Ventas inherited when it merged with Nationwide Health Properties many years ago, Anderson explains. Ventas just re-upped its exclusivity arrangement with the company for the next ten years, he says.

A Lower Risk Profile

What is strange, he says is that “cap rates on medical office assets that are trading hands are still quite low, but nonetheless REITs are maintaining a fair amount of attention toward the space.” Anderson also points out that medical office assets are known for their stability and relatively lackluster growth while skilled nursing is a higher returning asset class that comes with higher risk.

His tentative takeaway: there is possibly a return to risk-off mentality around the corner for healthcare REITs. “Maybe REITs are becoming buyers of medical offices simply because of their low risk orientation, even though the asset class remains quite expensive.”


Source:  GlobeSt.